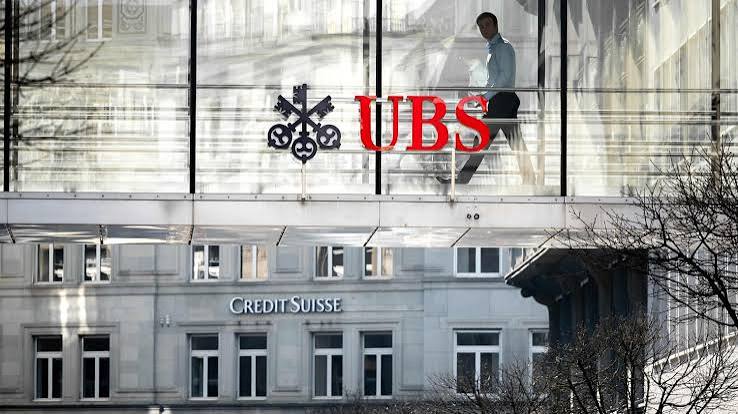
Switzerland is moving ahead with a major overhaul of its banking rules following the collapse of Credit Suisse, with the government seeking stronger safeguards to prevent another financial crisis and reduce the risk that taxpayers could be forced to rescue a major bank.
The proposed reforms are part of Switzerland’s updated “too-big-to-fail” framework, developed after Credit Suisse was taken over by UBS in 2023. The government says the crisis exposed weaknesses in the existing regulatory system and showed that large banks need stronger capital, better crisis planning and more effective supervision.
One of the most important proposals would require systemically important Swiss banks to fully back their investments in foreign subsidiaries with Common Equity Tier 1 (CET1) capital. The measure is expected to have its biggest impact on UBS, which became Switzerland’s only globally significant bank after acquiring Credit Suisse. The Swiss government adopted the legislative proposal in April, and parliament is now considering the details.
The proposed capital rules have become one of the most closely watched issues in Switzerland’s financial sector. Under the government’s plan, UBS could eventually need to hold roughly $20 billion in additional common equity capital. The purpose is to make sure the bank has a larger financial cushion if problems emerge in its international operations and to reduce the potential burden on the Swiss government and taxpayers.
However, the proposal has also created a debate about how much regulation is appropriate. UBS has argued that requiring too much additional capital could reduce its competitiveness against large banks in the United States and Europe. Higher capital requirements can make a bank safer, but they can also reduce the amount of money available for lending, acquisitions, investments and shareholder returns.
Swiss lawmakers are therefore considering possible compromises. A parliamentary committee recently failed to reach an agreement on the proposed UBS capital rules and is expected to continue discussions later this month. Some lawmakers have suggested allowing UBS to meet part of the requirement through Additional Tier 1 (AT1) capital, which can be less expensive than ordinary common equity.
Capital requirements are only one part of the government’s broader reform package. Switzerland is also proposing stronger powers for its financial regulator, FINMA, allowing it to intervene earlier when banks face serious problems and impose tougher penalties. The reforms also include measures aimed at improving accountability among senior bank executives.
Executive compensation is another area receiving attention. Under the proposed rules, a larger portion of bonuses for senior executives at systemically important banks could be deferred for several years. Bonuses could also be reduced or recovered if executives are responsible for misconduct or major losses. The government says the aim is to encourage management to focus on long-term performance rather than taking excessive risks for short-term rewards.
The reforms would also improve banks’ ability to deal with financial emergencies. Switzerland is looking at stronger crisis-management arrangements and better access to central-bank liquidity during periods of severe stress. The Swiss National Bank has backed the government’s efforts, saying that full capital backing of foreign subsidiaries addresses a weakness highlighted by the Credit Suisse crisis.
The collapse of Credit Suisse remains an important warning for Switzerland because banking is a major part of the country’s economy. A failure of a large international bank can create problems far beyond the financial sector, affecting employment, investment, government finances and confidence in the country’s financial system.
The government therefore wants to make sure that another major bank failure would be easier to manage without requiring large amounts of public money. The broader goal is to ensure that banks have enough capital and liquidity to absorb losses and continue operating during periods of financial stress.
At the same time, Switzerland does not want to make its banking sector unnecessarily expensive or less competitive. Finding the right balance will be one of the biggest challenges for lawmakers as they finalise the new rules.
The consultation on several of the proposed regulatory measures is scheduled to remain open until November 19, 2026, while parliamentary discussions on the UBS capital framework are continuing.
For Switzerland, the lesson from Credit Suisse is straightforward: a bank can meet existing regulatory ratios and still face a crisis if confidence disappears quickly. The government’s new approach is therefore focused not only on minimum capital levels but also on management responsibility, supervision, liquidity and crisis preparedness.
If approved, the reforms would represent one of the most significant changes to Switzerland’s banking framework since the Credit Suisse collapse. The government hopes the tougher rules will strengthen financial stability while ensuring that future banking problems do not become a direct burden on Swiss taxpayers.